 Skip to Content

Florida Community Property Trusts: Potential Tax Benefits for Married Couples
 By: Mary Saunders, Esq.
Although Florida is not a community property state, Florida law allows married couples to create a Florida Community Property Trust and transfer selected assets into the trust. For couples who own highly appreciated investments, real estate, or business interests, this planning strategy may provide a significant capital gains income tax benefit when the first spouse dies.
The primary advantage is the potential for a full adjustment in tax basis for trust assets at the death of the first spouse, often referred to as a “double step-up in basis.” As a result, the surviving spouse may be able to sell appreciated assets with substantially reduced capital gains tax, and in some cases, little or no capital gains tax at all.
What Is a Florida Community Property Trust?
A Florida Community Property Trust allows married couples to elect community property treatment for assets transferred to a qualifying trust, even though Florida is not a community property state.
The Florida Community Property Trust Act, found in Sections 736.1501 through 736.1512, Florida Statutes, does not automatically convert marital assets into community property. Instead, spouses decide whether to create a Community Property Trust and which assets to transfer to it.
Under Florida Statute § 736.1503, the trust must meet specific requirements. Among them, the trust must:
- expressly declare that it is a community property trust under Florida law;
- have at least one qualified trustee;
- be signed by both spouses using the required trust execution formalities; and
- contain specific statutory language prominently at the beginning of the trust agreement.
The trust agreement can also establish how the property will be managed and whether the trust may be amended or revoked.
What Is the Tax Benefit of a Florida Community Property Trust?
One of the most important potential benefits involves the income tax basis of appreciated property when one spouse dies.
An asset’s tax basis generally determines taxable gain when the asset is sold. If you purchase an investment for $300,000 and later sell it for $1 million, the difference between the adjusted basis and the sale price generally determines the taxable gain.
Under federal tax law, certain inherited property receives a basis adjustment based on its fair market value at the owner’s death. For many assets jointly owned by spouses in Florida, the basis adjustment at the first spouse’s death generally applies only to the deceased spouse’s interest, resulting in a basis adjustment for only half of the asset.
Section 1014(b)(6) of the Internal Revenue Code provides different basis treatment for qualifying community property when one spouse dies. Florida’s Community Property Trust Act specifically addresses the application of this federal provision in Florida Statute § 736.1511.
When the federal requirements are satisfied, both the deceased spouse’s interest and the surviving spouse’s interest in qualifying community property may receive an adjustment in basis.
This potential adjustment of the entire asset is commonly known as a “double step-up in basis.”
How Does a Double Step-Up in Basis Work?
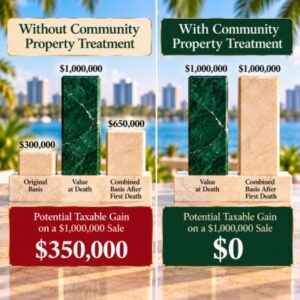 Suppose a married couple purchases an investment for $300,000. Years later, the investment is worth $1 million when the first spouse dies.
Without community property treatment, only the deceased spouse’s one-half interest may receive a basis adjustment. The surviving spouse’s one-half interest generally retains its original basis.
- Value at death: $1,000,000
- Combined basis after first death: approximately $650,000
- Potential taxable gain on a $1,000,000 sale: approximately $350,000
With community property treatment, both spouses’ interests may receive a basis adjustment to fair market value upon the first spouse’s death.
- Value at death: $1,000,000
- Combined basis after first death: approximately $1,000,000
- Potential taxable gain on a $1,000,000 sale: $0
As this example illustrates, a Florida Community Property Trust may significantly reduce capital gains tax for the surviving spouse by increasing the income tax basis of appreciated assets at the first spouse’s death.
What Assets Can Be Put in a Florida Community Property Trust?
Florida law allows spouses to classify any or all of their property as community property by transferring it to a qualifying Community Property Trust and providing in the trust that it is community property.
Assets that may warrant consideration include:
- investment accounts and marketable securities;
- appreciated real estate;
- certain business interests; and
- other assets with substantial unrealized appreciation.
Not every eligible asset is necessarily appropriate for a Community Property Trust. Retirement accounts and assets subject to special tax, contractual, or ownership rules require separate analysis. Before funding a Community Property Trust, an attorney should review each asset and consider the legal and tax consequences of changing its ownership and classification.
Can You Put a Florida Homestead in a Community Property Trust?
Under Florida Statute § 736.151, property transferred to or acquired by a Community Property Trust may continue to qualify, or may initially qualify, as the spouses’ Florida homestead, provided all applicable homestead requirements are satisfied.
The statute further provides that a qualifying transfer of homestead property to a Community Property Trust does not constitute a change of ownership for purposes of property tax reassessment.
Notwithstanding these benefits, Florida homestead law is complex and implicates constitutional restrictions on devise, creditor protections, ad valorem tax benefits, and other estate-planning considerations. The effect of transferring a homestead residence to a Community Property Trust should therefore be carefully evaluated on a case-by-case basis before any transfer is made.
Does a Community Property Trust Change Each Spouse’s Ownership Rights?
Potentially, yes. For that reason, the decision to create a Community Property Trust should involve more than a comparison of potential income tax benefits.
Under Florida Statute § 736.1505, property held in a qualifying Community Property Trust is treated as community property during the spouses’ marriage. The trust agreement generally governs each spouse’s rights to manage, control, and dispose of trust assets.
As a result, transferring property to a Community Property Trust may alter the spouses’ respective ownership interests, particularly when one spouse originally owned the property individually or when the spouses contribute assets of substantially different values. The implications can be even more significant where either spouse has children from a prior relationship, the parties have entered into a prenuptial or postnuptial agreement, or the spouses have different intentions regarding the ultimate disposition of their assets at death.
Although a Community Property Trust may offer important income tax advantages, those benefits should be weighed against the potential effects on ownership rights, creditor protection, inheritance planning, and existing marital property arrangements. A careful review of the spouses’ overall estate plan is therefore advisable before implementing a Community Property Trust.
What Happens to a Community Property Trust After the Death of a Spouse?
When one spouse dies, Florida law generally treats one-half of the Community Property Trust assets as belonging to the surviving spouse and one-half as belonging to the deceased spouse. The deceased spouse’s share then passes according to the estate plan and the terms of the trust.
Because of these rules, a Community Property Trust should be coordinated with the couple’s other planning documents. This is especially important for couples with children from prior relationships, unequal assets, or different goals for who should ultimately inherit family wealth. While a Community Property Trust can offer significant tax benefits, it should be integrated into the couple’s overall estate plan to ensure those benefits do not come at the expense of their intended inheritance plan.
What Happens to a Florida Community Property Trust in a Divorce?
If the spouses later divorce, Florida law provides special rules for determining each spouse’s rights in property held in a Community Property Trust. Assets that may have belonged primarily to one spouse before the trust was created could be treated differently after they are transferred to the trust.
For that reason, couples should not create a Community Property Trust simply because it may provide a favorable income tax result at death. They should also understand how the trust could affect property ownership, marital rights, existing prenuptial or postnuptial agreements, and the division of assets if the marriage ends in divorce. Careful planning before the trust is created is usually far easier than trying to address unintended consequences later.
Who Should Consider a Florida Community Property Trust?
A Florida Community Property Trust may be worth exploring for married couples who own highly appreciated assets, such as investment portfolios, real estate, closely held business interests, or other property with significant unrealized capital gains. In the right circumstances, the trust may provide substantial income tax benefits by preserving community property treatment and the resulting adjustment in income tax basis available at the death of a spouse.
However, a Community Property Trust is not appropriate for every married couple. Because it may affect ownership rights, inheritance planning, marital property arrangements, creditor rights, and the disposition of assets upon death or divorce, the potential tax benefits should be weighed against the broader legal and estate-planning consequences. A careful analysis of the couple’s assets, family circumstances, and estate-planning objectives is therefore essential before implementing this strategy.
An Important Tax-Law Caveat
 While the Florida Community Property Trust Act was enacted to allow married couples to elect community property treatment for trust assets, the Internal Revenue Service has not issued definitive guidance confirming that assets held in a Florida Community Property Trust qualify for a full basis adjustment under Internal Revenue Code § 1014(b)(6). As a result, although many practitioners believe the desired tax treatment is supported by existing law, the issue has not been conclusively resolved by the IRS or the courts.
Accordingly, a Florida Community Property Trust should be viewed as a potentially valuable tax-planning strategy, but not as a guaranteed method of obtaining a full step-up in basis in every case. Couples should consult with qualified legal and tax advisors to determine whether the potential benefits outweigh the uncertainties and other planning considerations.
Is a Florida Community Property Trust Right for You?
For the right married couple, a Florida Community Property Trust can offer an important estate planning opportunity, especially when assets have appreciated substantially over many years.
The potential for a double step-up in basis can be valuable, but tax treatment is only one part of the analysis. Before transferring property, couples should understand how the trust affects ownership and control during their lifetimes, what happens when the first spouse dies, and how the trust fits with their overall estate plan.
If you are married and own appreciated real estate, investments, business interests or other significant assets, a Florida estate planning attorney can review how those assets are titled and help determine whether a Community Property Trust makes sense for your family and long-term estate planning goals. I may be reached at mary.saunders@henlaw.com to schedule a consultation.