 Skip to Content
What Happens to Retirement Accounts in a Florida Divorce?
 By: Sarah Oquendo, Esq.
For many couples, retirement savings represent one of their largest assets after the family home. A 401(k), pension, IRA or other retirement account may have been built over decades and may be central to both spouses’ plans for life after work.
When a marriage ends, a common question is:
“What happens to those retirement savings?”
Under Florida law, retirement benefits accrued during the marriage are marital assets subject to equitable distribution. But that does not necessarily mean every dollar in a retirement account will be divided between the spouses.
When the account was established, when contributions were made, the type of retirement plan and how the benefits are ultimately divided can all affect the analysis.
Are Retirement Accounts Marital Property in Florida?
Florida law specifically provides that vested and nonvested benefits, rights and funds accrued during the marriage in retirement, pension, profit-sharing, annuity, deferred compensation and certain insurance plans and programs are marital assets subject to equitable distribution.
This can include retirement benefits even when the account or plan is held solely in one spouse’s name.
Florida courts begin equitable distribution with the premise that marital assets and liabilities should be divided equally, unless relevant statutory factors justify an unequal distribution. The key distinction is between the portion of the retirement benefit that is marital and any portion that may be nonmarital.
What If You Had the Retirement Account Before You Got Married?
Having a 401(k), IRA or pension before marriage does not necessarily make the entire account marital property.
Generally, assets acquired before marriage are nonmarital. For retirement benefits, this can mean that the portion attributable to premarital contributions may remain the nonmarital property of the spouse who owns the account, while benefits accrued during the marriage may be marital.
Determining those portions can become more complicated when an account has been open for many years and spans both the period before the marriage and the marriage itself.
Historical statements, employment records, plan documents and other financial records may therefore become important in determining what portion of the retirement asset is marital.
Consider This Scenario
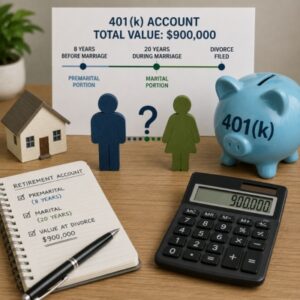 Suppose a husband began contributing to his employer’s 401(k) eight years before getting married. He continued making contributions throughout a 20-year marriage. When the couple files for divorce, the account is worth $900,000.
The fact that the 401(k) is titled only in the husband’s name does not mean the wife has no potential interest in it. At the same time, simply looking at the account’s $900,000 balance and dividing it in half may not properly account for the premarital portion.
The parties may need to determine what portion of the retirement asset is attributable to the marriage and what portion, if any, remains nonmarital. The same general issue can arise with pensions and other retirement benefits that began accruing before the marriage and continued accruing afterward.
How Are 401(k)s Divided in a Florida Divorce?
A 401(k) is an employer-sponsored retirement plan. When a marital interest in a qualified retirement plan is awarded to the other spouse in a divorce, implementing that division may require a Qualified Domestic Relations Order, commonly known as a QDRO.
A QDRO is a domestic relations order that meets applicable federal requirements and recognizes or assigns an alternate payee, often a former spouse, the right to receive all or a portion of a participant’s retirement plan benefits. The plan administrator determines whether the order satisfies the requirements to be treated as a QDRO.
The details matter. The divorce judgment or settlement agreement should clearly address how the retirement benefit is being divided, and the QDRO must be consistent with the final judgment or settlement agreement. Plan requirements should also be reviewed because retirement plans can have their own procedures for processing domestic relations orders.
A poorly drafted or delayed QDRO can create complications after the divorce is otherwise complete.
Are IRAs Divided the Same Way?
Not necessarily. An IRA is different from an employer-sponsored qualified retirement plan, and a QDRO generally is not the mechanism used to divide an IRA.
Instead, an IRA awarded or transferred between spouses as part of a divorce may be divided through a transfer incident to divorce when the applicable legal and tax requirements are satisfied.
This distinction matters because simply withdrawing money from a retirement account and writing a check to a former spouse can create tax consequences that might have been avoided through the appropriate transfer process.
The method used to divide a retirement asset should therefore be considered as carefully as the amount being divided.
What Happens to a Pension in a Florida Divorce?
Pensions can present different issues because the benefit may promise future monthly payments rather than consist solely of a current account balance. Florida law provides that vested and nonvested retirement benefits accrued during the marriage may be marital assets.
Determining the marital portion of a pension can require examining the period during which the benefits were earned, the terms of the pension plan and the employee spouse’s service before, during and sometimes after the marriage.
The method of distribution may also depend on the type of plan and the circumstances of the parties. For spouses approaching retirement, issues involving survivor benefits and the timing and form of future payments can be especially important.
What About Beneficiary Designations After a Florida Divorce?
Divorce can also raise questions about beneficiary designations associated with retirement accounts. Because retirement plans are governed by their plan documents and may be subject to federal law, individuals should not assume that a divorce automatically resolves every beneficiary designation.
Following a divorce, it can be important to review retirement accounts and beneficiary designations and determine whether changes are appropriate. The plan administrator’s procedures and applicable legal requirements should be followed when making any changes.
Does It Matter Whose Name Is on the Retirement Account?
Not necessarily. Florida’s equitable distribution law focuses on whether an asset is marital or nonmarital rather than simply whose name appears on the account.
A retirement account held entirely in one spouse’s name may still contain substantial marital assets if benefits were earned or contributions were made during the marriage.
Likewise, part of an individually titled account may remain nonmarital if it is attributable to assets acquired before the marriage or otherwise qualifies as nonmarital under Florida law.
What Is the Cut-Off Date for Retirement Contributions in a Florida Divorce?
 Florida law establishes a cut-off date for determining which assets and liabilities are classified as marital.
Generally, that date is the earliest date the parties enter into a valid separation agreement, another date expressly established by such an agreement or the date the petition for dissolution of marriage is filed.
The date used to value an asset is a separate question. Florida courts may use the date or dates the judge determines are just and equitable under the circumstances, and different assets may be valued as of different dates.
This distinction can matter with retirement accounts whose values fluctuate with the financial markets.
Is My Spouse Entitled to Half of My 401(k) in a Florida Divorce?
Not necessarily. Florida courts begin with the premise that marital assets and liabilities should be distributed equally, but that does not necessarily mean one spouse receives half of the total balance of the other spouse’s 401(k). The court must first determine what portion of the account is marital and what portion, if any, is nonmarital. Florida law also allows an unequal distribution of marital assets and liabilities when justified by the relevant statutory factors.
For example, depending on the financial circumstances, one spouse may retain a larger portion of a retirement account while the other receives another marital asset of comparable value.
The appropriate structure depends on the overall marital estate, the nature of the assets and the circumstances of the parties.
What Should You Gather If Divorce May Affect Your Retirement?
If retirement assets may be significant in a Florida divorce, gathering records early can help identify the marital and potentially nonmarital portions of those assets.
Useful documents may include current retirement account statements, older statements showing balances near the date of marriage, pension benefit statements, plan descriptions and records identifying contributions or service history.
For an account that predates the marriage, older records can be particularly important. Without documentation showing the account’s history, determining and proving a claimed nonmarital portion may become more difficult.
Bottom Line
Retirement accounts can be among the most valuable and financially significant assets divided in a Florida divorce.
Florida law generally treats retirement benefits accrued during the marriage as marital assets subject to equitable distribution, even when the account or plan is in only one spouse’s name. Benefits attributable to periods before the marriage may require a different analysis.
The type of retirement plan also matters. Dividing a 401(k), IRA and pension can involve different procedures, documentation and tax considerations.
Before agreeing to divide or transfer retirement assets, spouses should understand what portion may be marital, how the particular plan can be divided and how the proposed division fits within the overall financial settlement.
If you have questions about how a 401(k), pension, IRA or other retirement asset may be treated in a Florida divorce, contact Henderson Franklin’s Divorce, Marital and Family Law team. I may be reached at sarah.oquendo@henlaw.com to schedule a consultation.